Fast-track your intel and head to clear, actionable commercial leasing snapshots for Australia’s major CBDs. Combining market data, global impacts, national trends, and first-hand insight from our tenant advisory team.
A clear read on the Sydney CBD office market, combining the latest data with Tenant CS’ on-the-ground leasing insight.
Download snapshot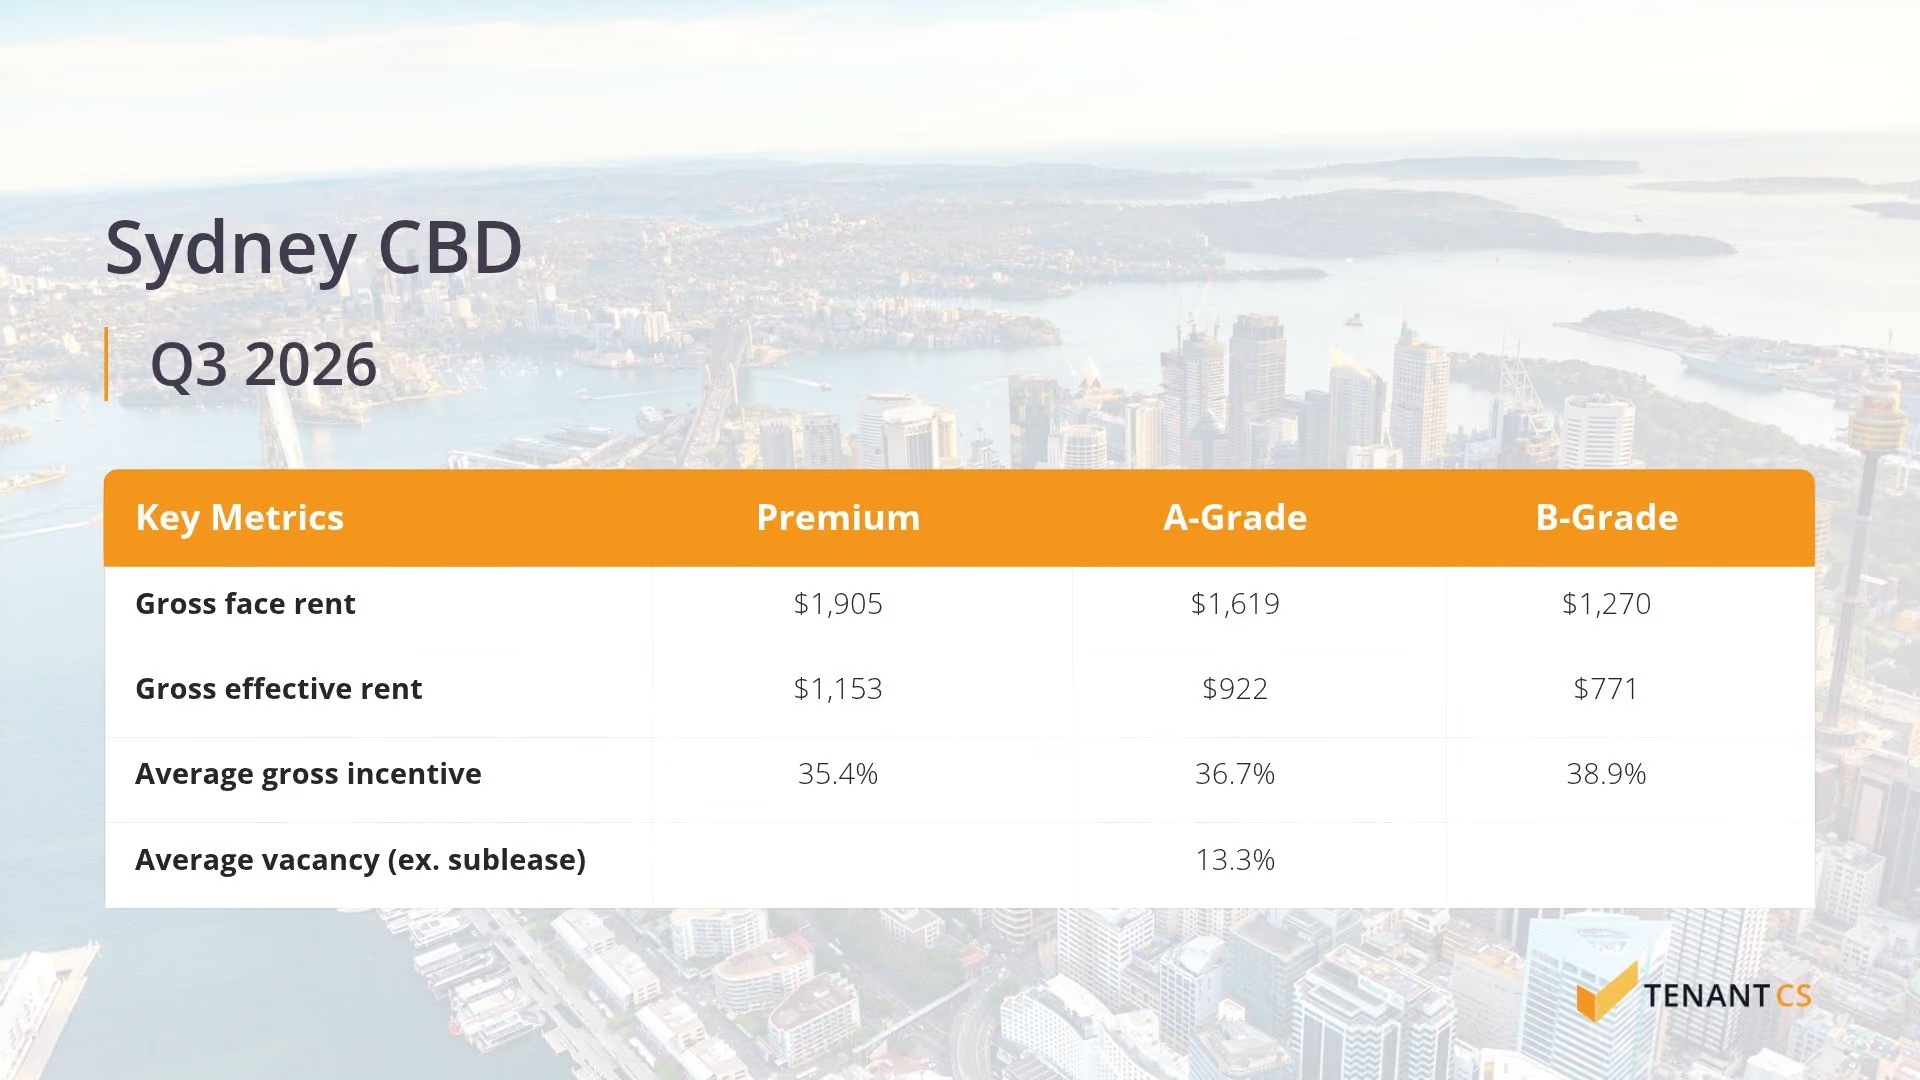
Headline net face rents in the Sydney CBD increased across all grades in Q3 2026, led by A-Grade (+2.9%), followed by Premium (+2.0%) and B-Grade (+1.4%). Outgoings also rose, most notably in Premium, where they increased 4.5% to $279 per sqm. Gross face rents now sit at $1,905 in Premium (+2.4%), $1,619 in A-Grade (+2.8%) and $1,270 in B-Grade (+1.2%), with more than a quarter of the Premium increase coming from higher outgoings rather than rent. Reported incentives were broadly unchanged, averaging 37.0% across all grades: 35.4% in Premium, 36.7% in A-Grade and 38.9% in B-Grade.
Effective rents, however, moved lower. Premium eased 3.9% over the quarter to $1,153 and A-Grade fell 7.2% to $922, while B-Grade was the only grade to record growth, rising 4.9% to $771. While this appears counterintuitive, there have been reports of a growing share of deals being struck on an effective basis. In these deals, the landlord and tenant agree an effective rent directly instead of a headline rent with a stated incentive. As a result, the full value of the concessions may not be captured in reported incentive averages.
Over the longer term, effective rents have made little progress. Since Q1 2020, Premium face rents have increased 29.6% while effective rents are down 0.7%. A-Grade face rents are up 25.0% while effective rents are down 9.9%, and B-Grade face rents are up 19.2% while effective rents are down 9.5%.
For tenants, headline rent growth overstates the real change in occupancy costs, although rising outgoings, particularly in Premium buildings, are adding to gross costs regardless of how rents are negotiated. Effective rent remains the key measure to negotiate on, and incentives continue to provide significant leverage across all grades.

Sydney CBD vacancy remained broadly stable at 13.3% as at July 2026, down from 13.8% in January, with vacancy tightening across all three grades over the first half of the year. Premium recorded the largest reduction, falling from 8.9% to 7.7%. A-Grade vacancy declined from 16.6% to 16.0%, and B-Grade edged lower from 16.0% to 15.8%.
The tightening in Premium and A-Grade has been supported by positive demand for higher-quality space, alongside limited new supply and withdrawals of existing stock. Premium availability is tightest at Barangaroo and in the Western Corridor, while larger Premium options are concentrated in a small number of buildings.
Vacancy varies considerably by precinct. Midtown has the highest vacancy at 17.9%, followed by the Western Corridor (13.9%), while the Core (11.0%), Southern (11.6%) and Walsh Bay (10.1%) precincts are tighter. Midtown A-Grade stock carries the highest vacancy in the CBD, offering the deepest pool of options for occupiers seeking quality space at a lower price point. Availability is also concentrated in a relatively small number of buildings, with around 40 buildings accounting for more than half of all vacant space, including large availabilities at Grosvenor Place, 270 Pitt Street and 52 Goulburn Street.
For tenants, this creates a two-tier market. Larger occupiers seeking contiguous Premium space face limited choice, while those willing to consider Midtown, the Western Corridor or high-quality A-Grade assets have access to a deeper pool of options and greater negotiating leverage.
On the supply side, no new office space has been delivered so far in 2026, with the next major supply wave set to begin late in the year. Three projects are currently under construction, collectively more than 60% pre-committed:
- Atlassian Central (58,000 sqm), due for completion in Q4 2026
- Chifley South (53,275 sqm), due for completion in Q3 2027
- 37–55 Pitt Street (63,000 sqm), due for completion in Q4 2027
With approximately 174,000 sqm of new space due between late 2026 and 2027, vacancy is expected to increase through H2 2027 and into 2028, as both available space within the new developments and backfill from relocating tenants enter the market. Beyond 2027, the development pipeline is limited, with challenging development conditions, including construction costs, restricting the next wave of new supply.
Sublease availability in the Sydney CBD remains low at approximately 0.7% of total stock, below historical averages. Available space is concentrated in a small number of buildings, with the largest current options at 255 Elizabeth Street and 680 George Street in Midtown. The most significant upcoming tranche is Atlassian’s 21,420 sqm sublease offering at Atlassian Central, expected to become available from late 2026, with commitment to date remaining low. A single offering of this size would materially lift total sublease availability, and gives occupiers a rare opportunity to secure brand-new space in a flagship building.
The Sydney CBD recorded 18,715 sqm of positive net absorption in H1 2026, with demand heavily weighted towards Premium stock. Premium recorded 19,388 sqm of positive absorption, while A-Grade was broadly flat at 434 sqm and B-Grade recorded -5,418 sqm.
Demand across the Sydney CBD continues to be led by tenants targeting quality space that suits their needs. Positive absorption was concentrated in the Core (13,491 sqm) and the Western Corridor (12,329 sqm), where stronger leasing terms are broadening tenant interest outside the Core. This supports the trend of tenants seeking a better balance of building quality, amenity and commercial terms.
Some of the recent notable commitments shaping the Sydney CBD market include:
- Asset Insure – 1 Margaret St – 3,500 sqm
- Stripe – 383 Kent St – 3,150 sqm
- Airwallex – 270 Pitt St – 2,000 sqm
- HWL Ebsworth – 5 Martin Place – expansion - 11,000 sqm
The longer-term impact of AI on office demand remains uncertain, but in the short term it is unlikely to translate directly into significantly smaller footprints. Growth in AI and technology businesses is creating new roles and new sources of office demand, while other organisations are restructuring teams as automation becomes more embedded.
As Consultant Michael Ly notes, AI is changing the structure of tech teams as much as the technology itself. This does not necessarily mean less space, but it can change the type of space businesses need, from desk numbers and meeting rooms to project areas, training and customer-facing space.
For occupiers, the longer-term impact of AI is therefore likely to be as much about how space is used as how much space is required. As roles and team structures evolve, flexibility within both the workplace and lease will become increasingly important when planning future office requirements.
In H2 2025, demand was concentrated in A-Grade, as tenants pursued quality space at a more competitive price point. In H1 2026, the data shows both flight to quality and flight to value, with Premium recording 19,388 sqm of positive net absorption.
Importantly, quality demand is not confined to the Core. The Western Corridor recorded 12,329 sqm of positive net absorption, close to the Core at 13,491 sqm, as Premium buildings in the precinct provide tenants with access to quality space on more competitive commercial terms. This has continued into Q3, with recent commitments by Stripe, Asset Insure and Airwallex all located in the Western Corridor and Midtown.
For occupiers, this means flight to value does not necessarily require a compromise on grade. Premium options outside the Core can offer the balance of building quality and stronger leasing terms that tenants are increasingly seeking, while Midtown A-Grade stock currently offers the deepest pool of available space in the CBD.
Size requirements are beginning to stabilise as hybrid workplace models mature and businesses become clearer on how they want people to use the office. Organisations are testing a range of approaches, from anchor days to activity-based and team-led models. Importantly, most now have a better handle on typical attendance patterns and space needs than they did two or three years ago. This is consistent with what our team, including Associate Director Courtney Magro, is seeing in recent tenant projects, where requirements are being framed with greater confidence around long-term workplace intent rather than short-term experimentation.
The sharp space give-backs of the immediate post-COVID period have eased, and this is now showing up in the sublease market: availability remains below the 10-year average, indicating fewer tenants are carrying large amounts of excess space. Against this backdrop of more right-sized footprints, elevated construction costs and the highest CBD vacancy in around three decades, fewer landlords are willing to deliver full whole-floor speculative fitouts. Instead, they are focusing on lighter refurbishments or smaller suite-style spec, with layouts and capex more closely aligned to increasingly specific, data-driven tenant briefs.
Sydney’s legal sector continues to favour Premium accommodation, with recent moves into 33 Alfred Street by Allens and Lander & Rogers, and Corrs into Quay Quarter Tower, reinforcing the preference for high-quality, well-located assets. This trend is continuing into the next development cycle, with MinterEllison and Baker McKenzie pre-committing to 37–55 Pitt Street, and Gilbert + Tobin to Chifley South both due for completion in 2027.
Our study of 75 mid- and top-tier Sydney law firms found that around 60% had upsized and 39% had downsized, with average tenure in the same building of approximately 7.5 years. The latest pre-commitments appear to be following the same trend, with firms securing larger footprints as part of their next move.
For legal occupiers, these commitments reinforce the importance of getting building quality, location and flexibility right from the outset, particularly when leasing decisions can shape workplace requirements for much of the next decade.
Sustainability remains a core filter for office occupiers, particularly larger corporates with formal decarbonisation targets. For many local and offshore tenants, strong ESG credentials are increasingly treated as a baseline requirement rather than a “nice to have”.
Tenants continue to favour buildings with strong Green Star, NABERS and/or WELL ratings. At the same time, recent analysis indicates only around 28% of Australian office buildings are on track to meet major tenants’ climate needs.
This is narrowing the pool of suitable accommodation and increasing the divide between newer or comprehensively refurbished assets and older stock.
The future Atlassian HQ at Tech Central (due for completion in November 2026) illustrates where demand is heading: a low-carbon, hybrid-timber, fully electric building targeting leading sustainability ratings. For tech and innovation-led occupiers, assets of this type align leasing decisions with climate commitments and employee expectations, while reducing exposure to future regulatory and carbon-cost risk.
Tech Central continues to strengthen as Sydney’s major technology and innovation precinct, supporting a $42 billion economy, almost 100,000 jobs and around 4,300 businesses. The precinct already includes major technology occupiers such as Atlassian, Canva, Block, SafetyCulture and Rokt, alongside universities, research institutions and a growing startup ecosystem.
Since the closure of the Sydney Startup Hub at Wynyard in 2025, the precinct has become the centre of the State’s startup support. The Tech Central Innovation Hub at 477 Pitt Street now provides 8,000 sqm across six floors for startups and scale-ups, operated by Stone & Chalk with Fishburners as anchor partner, and houses the Government’s International and Regional Landing Pads. This sits alongside a $38.5 million NSW Government commitment to further develop the precinct.
Atlassian Central topped out in July 2026 and is scheduled for completion in late 2026, with Atlassian expected to occupy from 2027. Its 21,420 sqm sublease offering will give other occupiers a rare entry point into the precinct’s flagship building. Beyond this, the next wave of office space remains some way off: Central Place Sydney (approximately 133,000 sqm) and TOGA Central are both approved, but neither has commenced construction or announced tenants.
Tech Central is increasingly becoming a genuine alternative to the traditional CBD Core, particularly for businesses seeking proximity to technology talent, universities, startups and other innovation-led organisations.
A clear read on the Melbourne CBD office market, combining the latest data with Tenant CS’ on-the-ground leasing insight.
Download snapshot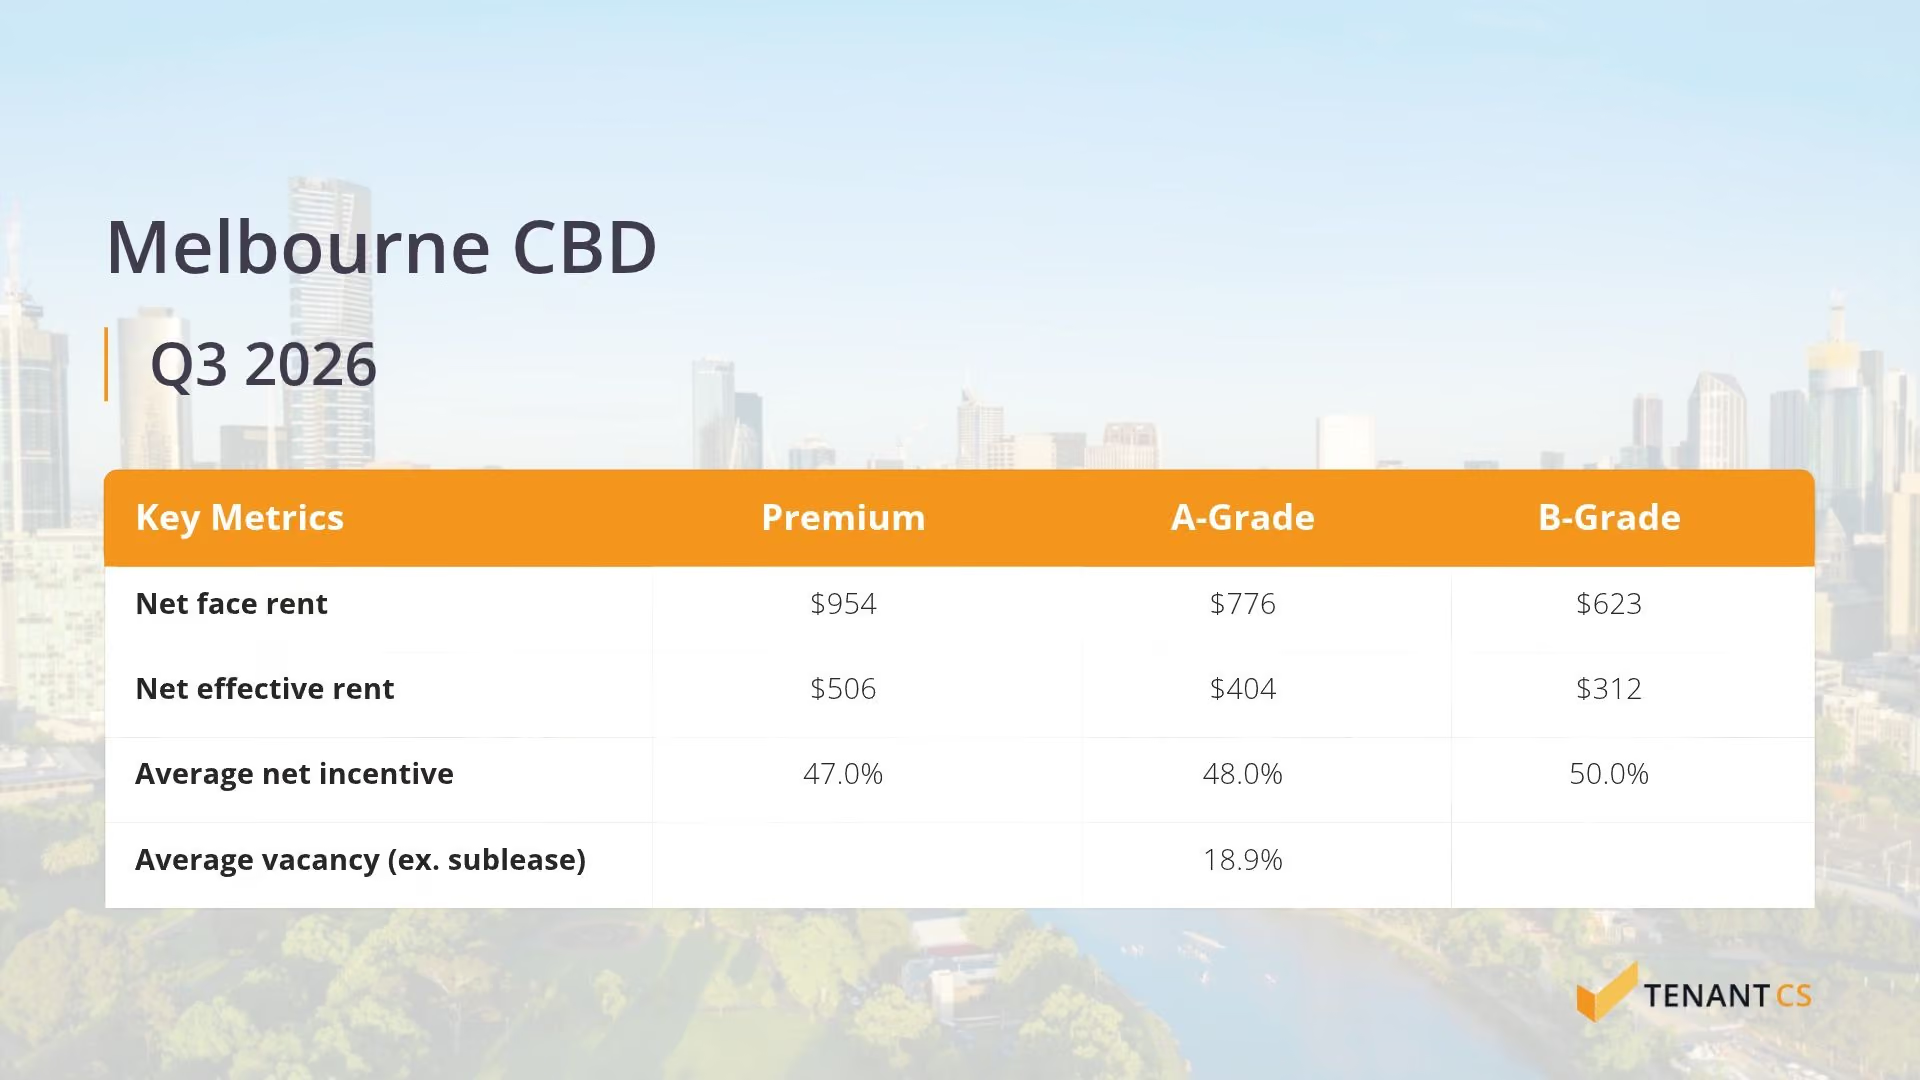
Net face rents eased marginally across all grades during Q3 2026. Premium-grade face rents fell 0.2% to $954, A-grade slipped 0.1% to $776, and B-grade declined 0.2% to $623. Face rents remain higher year-on-year, up 4.1%, 1.6% and 2.7% respectively.
Incentives held broadly steady across all grades during the quarter, at 47.0% for Premium, 48.0% for A-grade and 50.0% for B-grade.
Net effective rents were flat or slightly lower, holding at $506 for Premium, easing 0.2% to $404 for A-grade, and holding at $312 for B-grade. Market data expects rental growth to stay subdued over the next six to 12 months, leaving tenants well placed to negotiate on incentives and total occupancy cost.

As at July 2026, Melbourne CBD vacancy was 18.9%, marginally down from 19.0% in January, and remains the highest of any Australian capital city CBD. With total stock of 5.3 million sqm, around one million sqm of office space is vacant.
New supply added 1.3 percentage points to vacancy over the six months. This was more than offset by stock withdrawals, which removed 0.9 points, and positive tenant demand, which removed 0.5 points. Prime vacancy (19.0%) sits above secondary (18.6%), making Melbourne one of only two major CBDs where prime vacancy is higher.
More space is set to return to the market. Close to 100,000 sqm of backfill is expected over 2027 and 2028, including space released through the Victorian Government’s CBD consolidation. Relocations into 435 Bourke Street, due in Q4 2026, will also leave backfill elsewhere in the CBD.
For tenants, vacancy is unlikely to tighten in the near term. Prime options in particular remain deep, keeping negotiating leverage with occupiers.
Melbourne’s development pipeline is close to complete. 435 Bourke Street (62,500 sqm) is due in Q4 2026, followed by 720 Bourke Street (29,080 sqm) in Q2 2027, after which no major new projects are expected until the early 2030s. As construction slows, backfill takes its place. The Victorian Government plans to vacate close to 100,000 sqm across 121 Exhibition Street, 8 Nicholson Street and 50 Franklin Street over 2027 and 2028, adding to an already substantial pool of available space.
As a result, vacancy is unlikely to have peaked, even with tenant demand improving. Backfill is expected to keep upward pressure on vacancy through to 2028, before stock withdrawals and the lack of new construction support a gradual recovery ahead of the next development cycle. For tenants, choice and negotiating leverage should hold for at least the next two years, although large occupiers seeking brand-new premium space will have limited options until the 2030s.
As at July 2026, Melbourne CBD sublease vacancy had declined materially, from 64,000 sqm in January to 45,000 sqm, equivalent to 0.9% of total stock. Availability is now below the historical average, although Melbourne continues to record the highest volume of sublease space among the major Australian CBD markets.
Sublease space remains an attractive alternative to direct leasing, typically offering discounted effective rents, existing fitouts and shorter lease terms. This continues to provide cost savings and flexibility, particularly for tenants seeking near-term solutions or project space.
As at July 2026, Melbourne CBD demand had improved, with net absorption of 26,779 sqm over the first half of the year, following several years of weak or negative demand. By grade, demand was heavily concentrated in A-grade, which recorded 53,460 sqm of net absorption. Premium (–14,983 sqm), B-grade (–4,990 sqm) and C-grade (–6,913 sqm) all recorded negative absorption.
At a precinct level, the Eastern Core (+18,911 sqm) and Flagstaff (+15,455 sqm) led net absorption, while the Western Core (–10,634 sqm) was the weakest precinct. Docklands recorded modest positive absorption of 1,500 sqm.
The concentration of demand in A-grade reflects a continued preference for quality accommodation, while negative absorption across Premium and secondary grades shows that demand remains uneven across the market.
Commitments made during Q3 2026 include:
- MACS – 321 Exhibition Street (North Eastern) – 4,461 sqm
- Michelin – 30 Convention Centre Place (South Wharf) – 1,300 sqm (negotiated by Tenant CS)
- Sage Family Law – 469 La Trobe Street (Flagstaff) – 731 sqm
- Williams Winter – 555 Lonsdale Street (Western Core) – 640 sqm
- Rodd & Gunn – 226 Flinders Lane (Civic) – 544 sqm
Office assets are returning to market in the Melbourne CBD after a record low in sales. Only $74m of major transactions took place over the first three quarters of 2026. Heading to market in Q4 is $2bn of office stock, including 11 Exhibition Street, a 50% stake in Olderfleet at 477 Collins Street, a 50% stake in CBW and the 60 Collins Street development site. Some owners are selling to repair their balance sheets, including Suntec REIT, which is selling its Olderfleet stake to cut debt. Buyers remain cautious, with major investors avoiding Melbourne over high vacancy, elevated incentives, work-from-home uncertainty and property taxes.
With government backfill still to come and vacancy near 19% for several years, the wave of buildings coming to market suggests some owners aren’t banking on a quick recovery. For tenants, it’s a sign that favourable leasing conditions could last longer than current forecasts suggest.
Landlords are increasing investment in third-space amenity across Melbourne CBD buildings in response to growing demand from tenants and employers for greater functionality outside the traditional tenancy. Larger shared boardrooms are increasingly being replaced by smaller meeting rooms offered on a pay-per-use or first-come, first-served basis, giving tenants access to additional meeting capacity without carrying that space within their permanent footprint.
Demand is also broadening beyond meeting and collaboration spaces toward wellness-focused amenity. Mini gyms, recovery areas and purpose-built rooms for rest, faith, parents and first aid are becoming more common, alongside continued investment in end-of-trip facilities including bike storage, showers and EV charging.
For tenants, these facilities can reduce the need to replicate certain functions within their own tenancy while supporting employee experience and workplace attendance. As employers place greater emphasis on attracting staff into the office, the quality and functionality of third-space amenity is becoming a more important consideration when comparing buildings.
The Victorian Government’s proposed right to work from home has stalled ahead of the state election. The Bill would give eligible employees the right to work from home two days a week where reasonable. It passed the Legislative Assembly in July, and following the change of Premier, its start date had already been pushed back from September 2026 to July 2027.
In September, the Legislative Council referred the Bill to a select committee and deferred debate until the committee reports. With no report delivered, the Bill is set to lapse when Parliament expires on 3 November. Labor has committed to legislating a work-from-home right if re-elected, so the outcome now rests on the 28 November election.
The uncertainty matters for Melbourne, which has the highest CBD vacancy in the country at 18.9%, with significant government backfill still to come.
Whatever the result, hybrid work is already shaping space decisions. As leases approach expiry, businesses are increasingly sizing their next premises on actual office attendance rather than headcount. For tenants, the practical response is to plan for uncertainty: base space requirements on attendance data, and negotiate flexibility, such as contraction options, break clauses and shorter terms, so the footprint can adjust if a work-from-home right is legislated.
As noted by Jared Kroeger, a renewed shift toward A-Grade buildings is starting to emerge across the Melbourne CBD, particularly in assets that offer stronger workplace amenity and a more considered occupier experience.
“Tenants are still cost-conscious, but many are now looking more closely at how a building supports staff experience day-to-day. Buildings with strong amenity (whether that’s third spaces, upgraded lift lobbies, or end-of-trip facilities) are standing out. It’s less about a traditional flight-to-quality, and more about being selective. Tenants are willing to move up the quality curve, but only where the value is clear.”
H1 2026 leasing data supports this trend, with A-Grade the only major grade to record positive net absorption, while Premium, B-Grade and C-Grade all went backwards.
Despite this demand, A-Grade availability has grown. A-Grade vacancy rose from 20.6% in January to 20.8% in July, representing 564,198 sqm, as new supply added more space than tenants absorbed. Prime stock accounts for almost three quarters of all vacant space across the CBD. The depth of available A-Grade accommodation has created strong competition between landlords, providing tenants with access to higher-quality buildings, strong incentives and increasingly competitive fitted options.
The combination of significant availability and competitive terms is allowing tenants to achieve better value for their occupancy cost, with higher-quality accommodation becoming increasingly attractive relative to lower-grade alternatives. Tenants are taking advantage of these conditions, but with A-Grade vacancy still rising, it remains a highly competitive market for landlords rather than a constrained market for tenants.
From 1 January 2026, the Melbourne congestion levy on off-street parking rose sharply, with Category 1 (CBD) rising from $1,750 to $3,030 per bay per year and Category 2 increasing from $1,240 to $2,150. The Category 2 area has also expanded into Burnley, Cremorne, South Yarra, Windsor and parts of Richmond, Abbotsford and Prahran, while the Queen Victoria Market area moved to the lower Category 2 rate.
For tenants with significant parking requirements, the increase can materially affect total occupancy costs where the levy is passed through via parking charges or other property costs. The expansion is particularly relevant when comparing CBD and fringe locations, as several inner-eastern precincts that previously sat outside the levy are now subject to the Category 2 rate. Parking requirements and associated costs should therefore be considered alongside rent, incentives, transport access and staff catchments when assessing future leasing options.
Fitted space continues to lease ahead of vacant space, with a clear hierarchy emerging in the sub-300 sqm market. Well-designed, modern spec suites are leasing faster than older or more generic fitouts, as smaller tenants prioritise quality, convenience and avoiding upfront fitout costs.
Older spec suites are still leasing but typically require stronger incentives or landlord contributions towards refresh works to compete with newer, better-presented options. For tenants, the depth of fitted options provides an opportunity to compare not only rental terms, but the quality and usability of the existing fitout and the overall cost of occupation.
ESG credentials remain an important consideration for Melbourne tenants, particularly larger corporates with sustainability targets and reporting requirements. Buildings with strong NABERS ratings, modern services, and better staff amenity continue to attract interest, particularly across A-Grade stock, where demand has improved materially over the past six months.
The significant availability of A-Grade space is providing tenants with greater access to buildings with stronger ESG credentials without necessarily moving to the Premium end of the market. This aligns with the broader shift toward A-Grade, while B-Grade demand remained negative.
For tenants, ESG is increasingly considered alongside building quality, amenity and overall value rather than in isolation. The depth of available A-Grade stock means tenants can be more selective and incorporate sustainability requirements into a broader assessment of workplace quality and occupancy cost.
A clear read on the Brisbane CBD office market, combining the latest data with Tenant CS’ on-the-ground leasing insight.
Download snapshot
Over the year, effective rents in the Brisbane CBD have grown faster than face rents across all grades. Premium face rents increased 5.3% to $1,323 while effective rents rose 6.7% to $898. A-Grade face rents are up 5.1% to $1,034 against effective growth of 8.5% to $699, and B-Grade face rents are up 3.3% to $837 against 5.4% to $525. Over the quarter, effective rents rose 1.2% in Premium, 1.7% in A-Grade and 0.4% in B-Grade.
Reported incentives compressed 1.0 percentage point in both A-Grade and B-Grade over the year, to 33.5% and 37.5% respectively, adding to effective rental growth on top of rising face rents. Premium incentives were unchanged at 33.0%, so Premium effective growth largely reflects higher face rents.
For tenants, headline rent growth understates the real increase in occupancy costs. Effective rent remains the key measure to negotiate on, and tenants should benchmark offers against recent effective deals in the building rather than headline incentive levels.
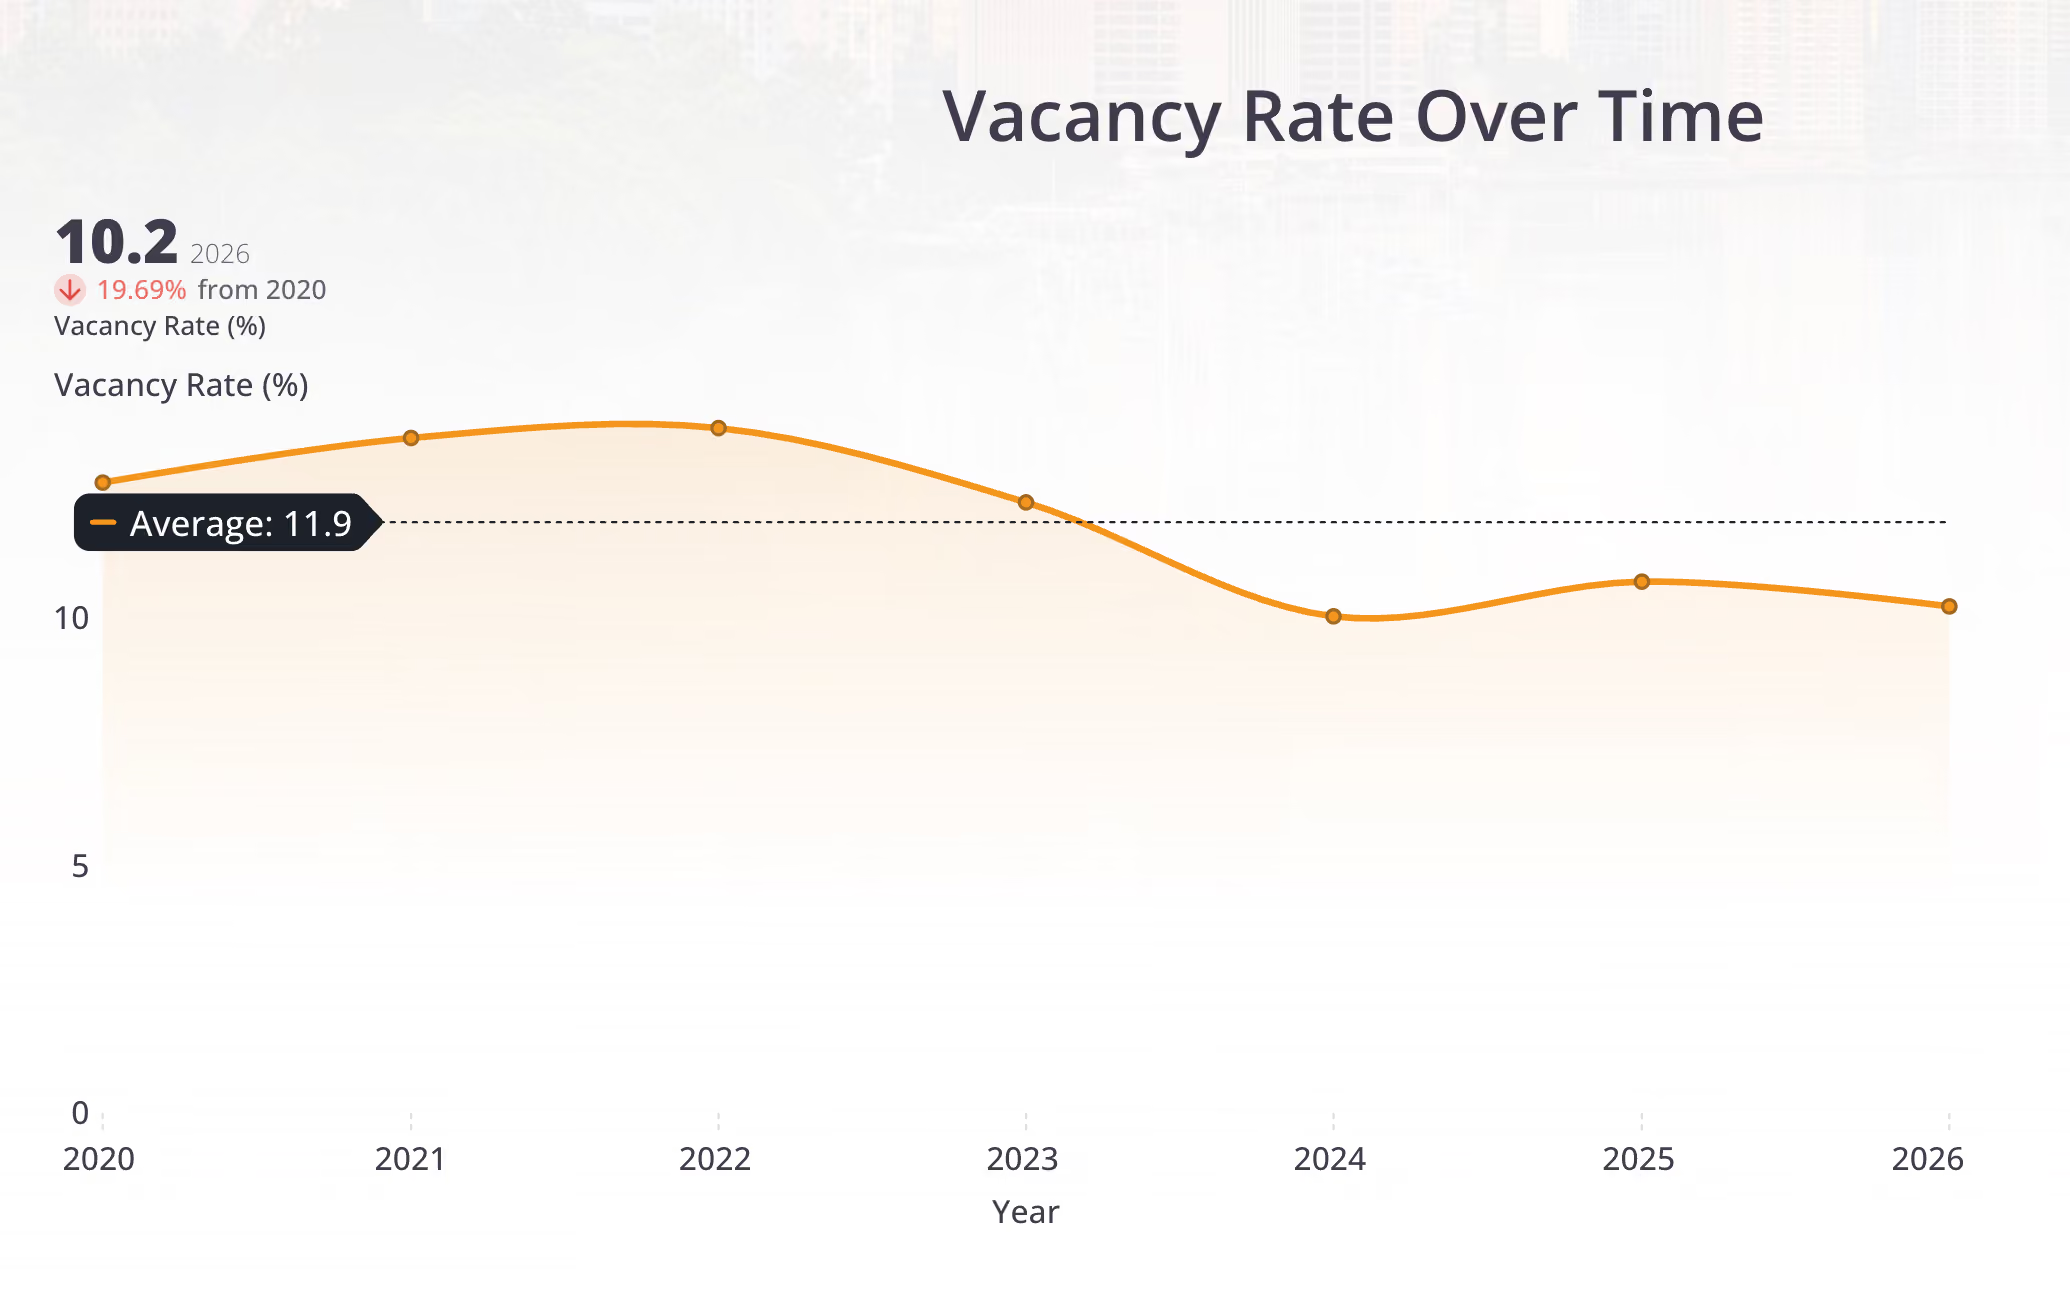
As at July 2026, Brisbane CBD vacancy was 10.2%, down 1.6 percentage points over six months. This was the lowest vacancy rate and the largest fall among Australia’s major CBD markets, although vacancy remains above Brisbane’s historical average.
Vacancy fell across all grades. A-Grade declined 2.4 percentage points to 8.3%, Premium fell 1.7 percentage points to 6.5%, and B-Grade decreased 1.5 percentage points to 13.3%.
For tenants, quality options are narrowing, particularly for larger contiguous requirements. Occupiers with lease events in the next two to three years should test the market early, while B-Grade continues to offer more choice and greater negotiating leverage.
Brisbane CBD’s supply outlook is unchanged, with no major new CBD development completing in 2026. The next significant additions are 450 Queen Street in 2027 and Waterfront Brisbane North Tower in 2028, while tenant relocations will progressively release backfill space across existing assets.
Upcoming supply:
- 450 Queen Street – 17,500 sqm – Completion 2027
- Waterfront Brisbane (North Tower) – 73,000 sqm – Completion 2028 – 72% pre-committed
Sublease availability in the Brisbane CBD has increased in Q3 to 0.9% of total stock, circa 21,000 sqm. Prime buildings hold most of this space, accounting for circa 13,700 sqm, with the largest tranches at:
- 180 Ann Street – circa 3,300 sqm
- Heritage Lanes, 80 Ann Street – circa 2,800 sqm
- 60 Edward Street – circa 2,800 sqm
For tenants, the concentration of sublease space in Prime buildings offers an alternative to tightening direct Prime availability, subject to remaining lease term and fitout condition.
Tenant demand strengthened over the first half of 2026, with the Brisbane CBD recording 38,785 sqm of positive net absorption, significantly above the historical six-month average of 10,165 sqm.
PCA data shows A-Grade (+25,384 sqm) accounted for the largest share of demand, followed by B-Grade (+10,622 sqm) and Premium (+7,756 sqm). D-Grade recorded a small positive result (+1,939 sqm), while C-Grade was the only grade to record negative demand (–6,916 sqm).
CIMIC’s move from the Fringe into 12 Creek Street was among the larger commitments behind this result. Demand is expected to remain positive, with potential additional requirements emerging as planning for the 2032 Olympics gains momentum.
Some of the commitments which will shape the future of the Brisbane CBD include:
- Christie System Services – 225 Edward St – 3,456 sqm
- ConocoPhillips – 123 Albert St – 3,000 sqm
- CIMIC – 12 Creek St – 8,000 sqm
- Legal Aid – 400 George St – 6,000 sqm
Waterfront Brisbane’s North Tower will introduce 73,000 sqm of new office space, materially changing the riverfront skyline and the outlook from a number of existing CBD buildings. The scale and positioning of the tower will affect views not only from buildings directly behind the development, but potentially from tenancies with oblique views across or alongside the site.
For tenants currently benefiting from river, Story Bridge or broader eastern views, this is an important consideration when entering a new lease or approaching a renewal. Natural light and outlook can influence rental rates and the relative value of a tenancy, so tenants should consider how these attributes may change over the proposed lease term.
Tenants potentially affected should use the development as an opportunity to review their longer-term space requirements and workplace strategy before committing to their existing accommodation. Engaging a tenant representative early can help tenants understand the potential impact on their tenancy, assess alternative options and ensure future changes to views and amenity are reflected in upcoming lease and rental negotiations.
Speculative fitouts continue to provide ready-to-occupy options across the Brisbane CBD, although many remain tailored towards the traditional legal and resources sectors, with private offices and enclosed rooms positioned along perimeter glazing.
These layouts can generally be tailored to suit different workplace requirements, particularly where tenants engage before construction is complete. Early engagement can provide greater input into layout and design, allowing occupiers to achieve a more open, collaborative or business-specific solution while retaining the cost and timing benefits of a speculative fitout.
Elevated fitout and construction costs continue to make fitted space a key consideration for tenants looking to reduce upfront capital expenditure and shorten delivery timeframes. However, the quality of existing fitted stock is becoming increasingly important as Brisbane CBD vacancy tightens.
For smaller occupiers seeking approximately 200–400 sqm, the quality of existing fitted options remains mixed. Many available fitouts are older, while some require meaningful modification before they can provide a contemporary workplace. Speculative suites continue to provide an alternative, although design and quality can vary considerably between buildings.
For tenants, this creates a distinction between fitted space and genuinely move-in-ready space. Occupiers should assess the age, condition and suitability of an existing fitout alongside the commercial terms, particularly where modification costs could materially reduce the benefit of taking fitted accommodation.
Brisbane’s future supply pipeline remains limited, with no major new CBD development completing in 2026 and the next significant additions being 450 Queen Street in 2027 and Waterfront Brisbane North Tower in 2028. At the same time, vacancy tightened to 10.2% as at July 2026, with Premium vacancy at 6.5% and A-Grade at 8.3%, following strong positive absorption during the first half of 2026.
For tenants, particularly those requiring larger contiguous areas, this is increasing the importance of early market engagement and forward planning. With incentives tightening and effective rents continuing to rise, deferring decisions has not improved terms over the past year. Occupiers approaching lease expiry should consider future backfill and development opportunities early to preserve choice and negotiating leverage.
B-Grade recorded 10,622 sqm of positive net absorption during the first half of 2026, with vacancy falling from 14.8% to 13.3% as at July 2026. With Prime vacancy at 7.7%, B-Grade remains the segment with the most availability.
For tenants, upgraded B-Grade assets can provide a viable alternative to increasingly constrained Prime accommodation. B-Grade also offers the highest incentives (37.5%) and the slowest effective rental growth (5.4% over the year). However, the B-Grade market remains varied, making building quality, fitout and capital investment important when assessing value.
Sustainability and building performance remain important considerations for corporate and government occupiers, with NABERS ratings, energy efficiency and broader ESG requirements increasingly forming part of tenant shortlisting criteria.
For tenants, sustainability is being considered alongside occupancy cost, building amenity and workplace quality, contributing to greater differentiation between upgraded assets and older buildings where capital investment and environmental performance remain limited.
Follow us
Share this article
Take a look at our latest office snapshot of the CBD office leasing markets across Australia including our rent, incentive and vacancy forecasts.
A few clear shifts are starting to emerge in 2026, from how space is being delivered to how tenants are using it. Our team shares on-the-ground insights into fitted space, workplace design, and evolving leasing priorities across the major CBDs.
Landlords usually hold the advantage at the negotiating table. These six strategies help commercial tenants build real leverage before they sign, whether renewing or relocating.
Tenant CS helps tenants across Australia gain clarity, confidence and control in their lease negotiations. We back you with industry intel, independent research tools, negotiation expertise and on-the-ground experience.
Always conflict-free. Always on your side.